
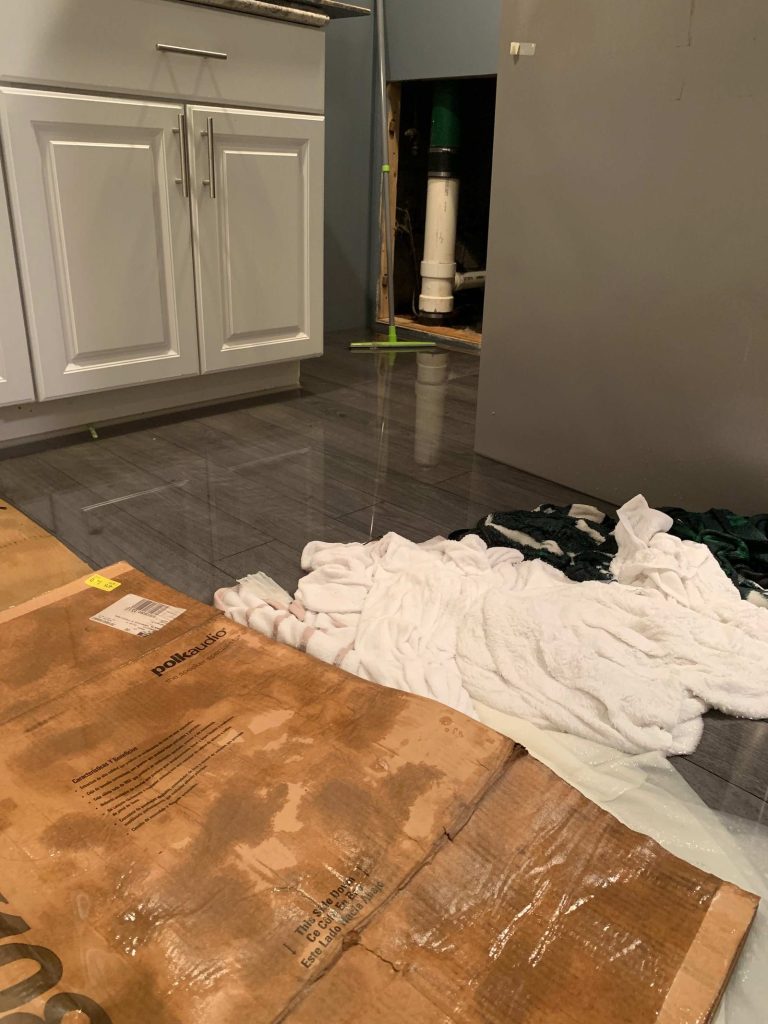
Water damage insurance coverage in NY usually depends on where the water came from and how fast it happened. Sudden leaks, such as a burst pipe, are often covered by a homeowners policy. Flood, slow leaks and sewer backups usually are not, unless the right coverage was added. Reading your policy early saves surprises.
Written by the Bowerman Cleaning and Restoration Team · April 10, 2026
Key Takeaways
- Sudden and accidental water damage is the type most policies cover.
- Standard NY homeowners policies do not cover flood, which needs a separate policy.
- Sewer and sump backups usually need a water backup endorsement.
- Photos, moisture readings and drying logs make a claim easier to support.
In This Guide
- What Water Damage Does Insurance Usually Cover?
- Why Are Flood and Sewer Backup Treated Differently?
- How Do You File a Water Damage Insurance Claim?
- Why Do Water Damage Claims Get Denied?
- What Should NY Homeowners Check in Their Policy?
- Water Damage Insurance Coverage FAQs
What Water Damage Does Insurance Usually Cover?
Short answer: sudden, accidental water from inside the home. Policies differ, so your own policy wording always controls. Still, most claims fall into a few common patterns.
| Source of water | Usually covered by a standard policy? | Notes |
|---|---|---|
| Burst or frozen pipe | Often yes | Coverage can depend on whether heat was kept on |
| Failed water heater or supply line | Often yes | The failed part itself may not be covered |
| Roof leak from storm damage | Often yes | Wear and tear leaks are usually excluded |
| Slow leak over weeks or months | Often no | Treated as maintenance or gradual damage |
| Sewer or sump pump backup | Only with an endorsement | Check for water backup coverage |
| Flood or surface water | No | Needs a separate flood policy |
Use this table as a starting point, not a promise. Call your agent or insurer to confirm what your policy says.
Why Are Flood and Sewer Backup Treated Differently?
Short answer: they are excluded from standard homeowners policies in New York. According to the New York State Department of Financial Services, standard homeowners and tenants policies do not cover flood damage. That coverage comes from a separate flood policy, usually through the National Flood Insurance Program.
Sewer and sump backups sit in a gray area. As NY DFS explains, they are generally covered only if a water backup endorsement was added. So if your basement is finished, it is worth asking your agent about that add-on before the next storm.
How Do You File a Water Damage Insurance Claim?
Short answer: stop the water, document it, report it and keep records. Following these steps keeps a claim organized from the first day.
- Stop the damage. Shut off the water and start drying. Policies generally expect you to prevent further damage.
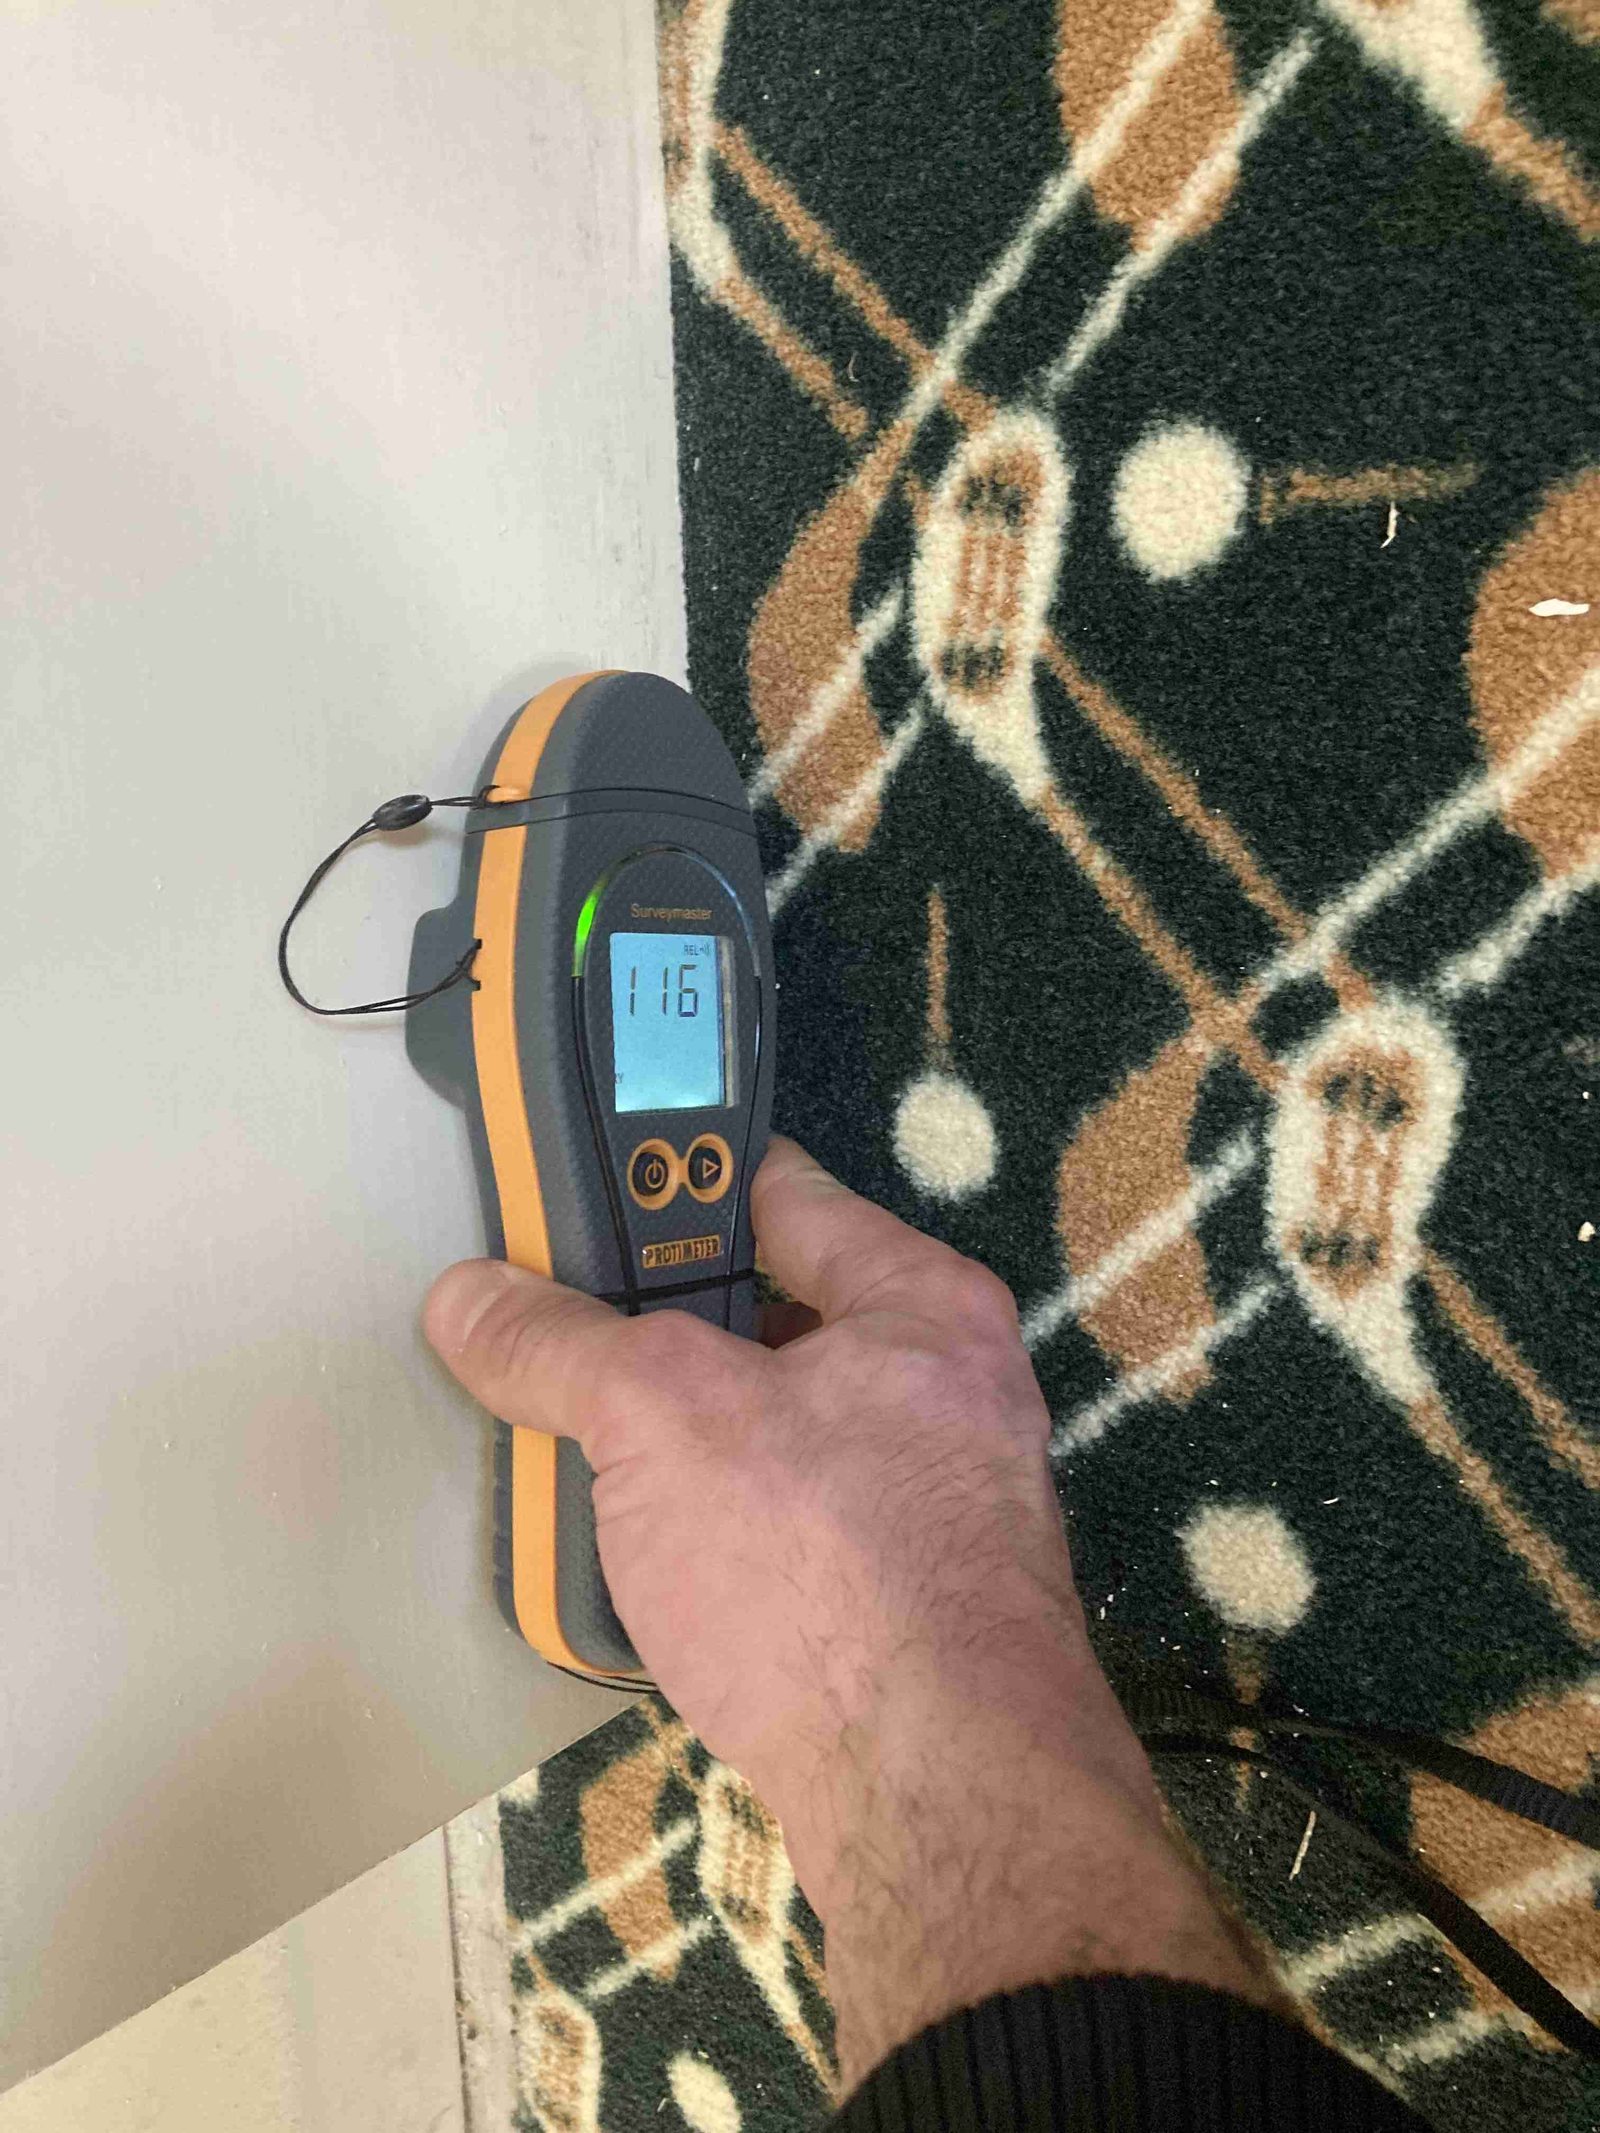
- Document the loss. Take photos and video of the source, every wet area and damaged items before anything is moved.
- Report the claim. Call your insurer, write down the claim number and ask what they need from you.
- Keep damaged items. Set aside damaged items until the adjuster sees them or says you can discard them.
- Collect drying records. Ask the restoration contractor for moisture readings, photos and drying logs.
- Review the estimate. Compare the adjuster’s estimate with the restoration and rebuild scope before you sign off.
This page on filing a claim outlines what insurers typically ask for. For a deeper look at coverage questions, read does homeowners insurance cover water restoration.
Need drying records for your claim? Bowerman Cleaning & Restoration answers 24/7 across Westchester County.
Why Do Water Damage Claims Get Denied?
Short answer: most denials come down to gradual damage, flood or late reporting. Knowing the common reasons helps you avoid them.
- Gradual damage. A leak that dripped for months is often treated as a maintenance issue.
- Flood exclusion. Surface water from storms is not covered under a standard policy.
- No backup endorsement. Sewer and sump backups need added coverage.
- Late reporting. Waiting can make it harder to show what caused the damage.
- Mold from delays. If water was left to sit, resulting mold may be limited or excluded.
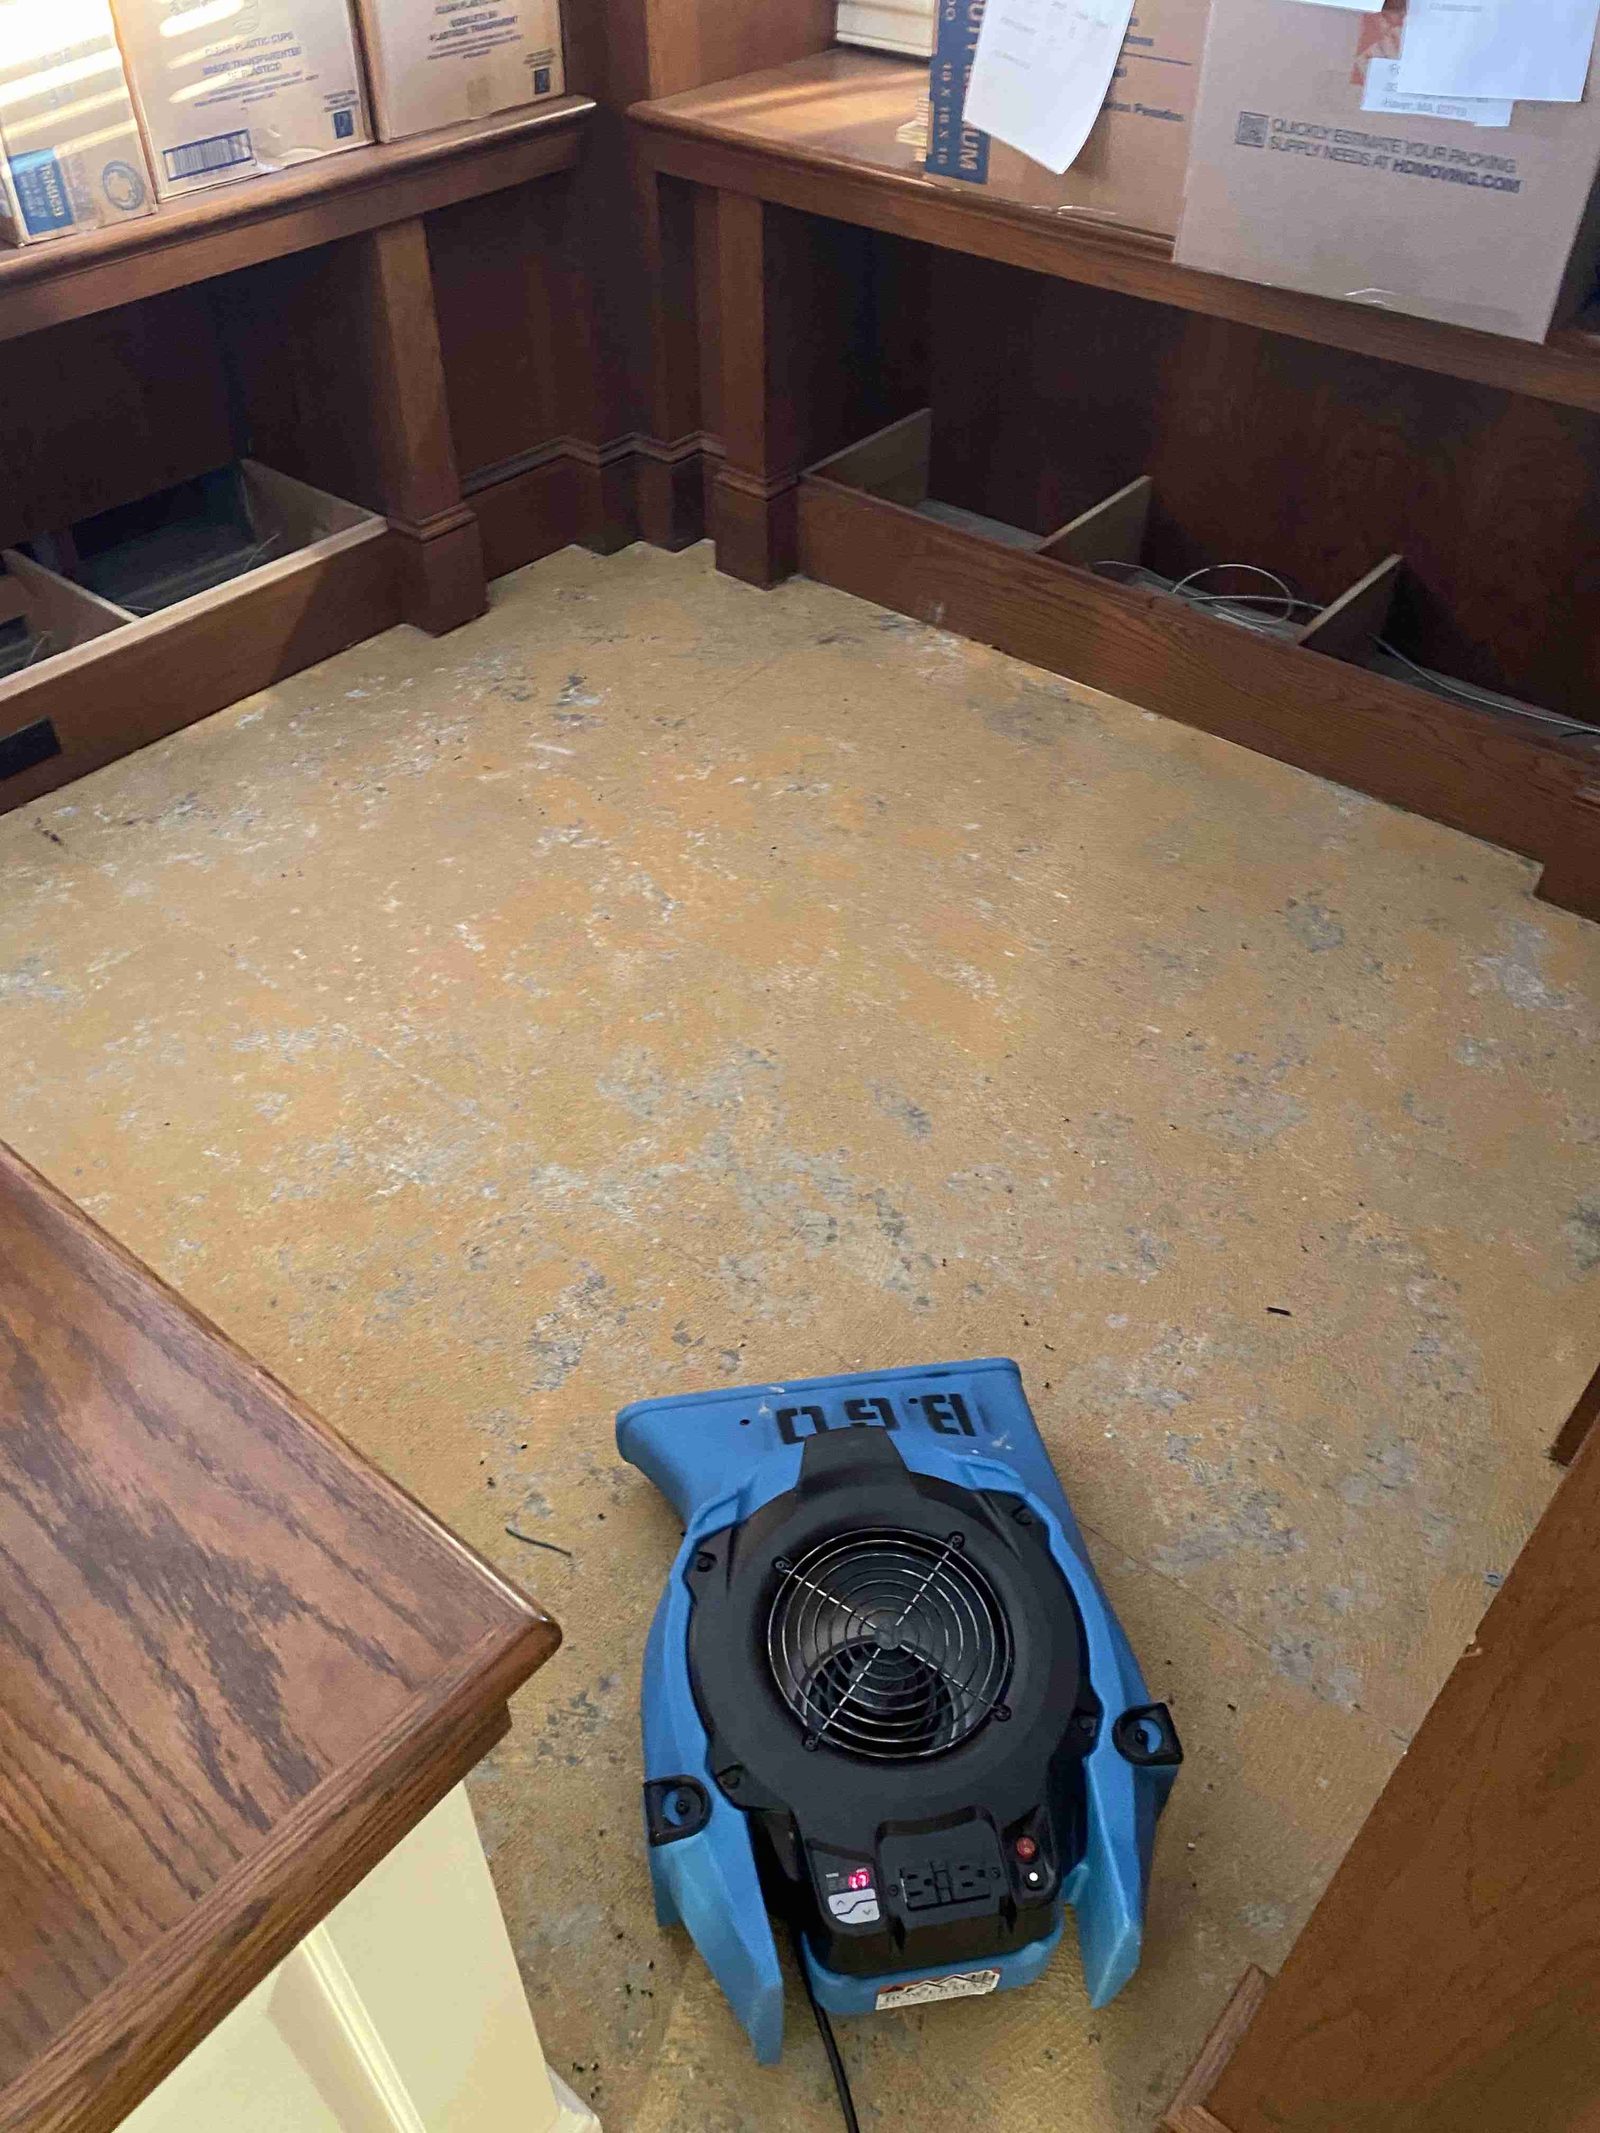
Fast drying helps on several of these points. The EPA’s guide to mold and moisture advises drying wet areas within 24 to 48 hours to help prevent mold growth. This overview of what water damage restoration is explains the full process. A related look at water damage restoration cost shows how the same documentation can affect the bill. This page on water damage restoration services outlines a typical scope an insurer may see.
What Should NY Homeowners Check in Their Policy?
Short answer: flood coverage, water backup coverage and the deductible.
If you live near the coast or a river, ask whether a separate flood policy makes sense, since flood is excluded from standard NY homeowners policies. If you have a finished basement with a sump pump, check for a water backup endorsement. Condo and co-op owners should also review the building’s master policy, because it may cover some parts of the unit and not others.
Water Damage Insurance Coverage FAQs
Does homeowners insurance cover a burst pipe in NY?
Often, yes, because a burst pipe is usually sudden and accidental. However, coverage can depend on the cause. For example, a frozen pipe in a home left without heat may be treated differently. Check your policy wording.
Is a flooded basement covered by homeowners insurance?
It depends on the source. Water from a burst pipe may be covered. Water from rain or rising groundwater is flood, which needs a separate policy. A sump pump failure usually needs a water backup endorsement.
Should I call my insurer or a restoration contractor first?
Make the area safe and stop the water, then call both. Starting drying quickly helps prevent more damage, which policies generally expect. Take photos before anything is moved.
Can a restoration contractor deal with my insurer for me?
Many restoration contractors share photos, readings and estimates with insurers. You are still the policyholder, though, so you make the final decisions on the claim and the repairs.
Does insurance pay for mold after water damage?
Sometimes, when the mold resulted from a covered, sudden leak. Many policies limit or exclude mold from long-term leaks or delays. Fast drying is the easiest way to avoid a mold question altogether.
Does renters insurance cover water damage?
Renters insurance usually covers your belongings, not the building. The landlord’s policy typically covers the structure. Like homeowners policies, renters policies generally exclude flood, so check your coverage and report damage quickly.
Need help documenting water damage in Westchester County? Bowerman Restoration LLC d/b/a Bowerman Cleaning & Restoration, 7 Intervale Street, White Plains, NY 10606, answers 24/7 at (844) 269-3762.